Home Insurance
High-Value Home Insurance: When Standard Coverage Isn't Enough
As property values in Durham Region and across Ontario have appreciated significantly, many homeowners are now carrying a standard home insurance policy on a property that it was never designed to protect. High-value home insurance is a different product — with meaningfully different terms.
What Makes a Home "High Value"?
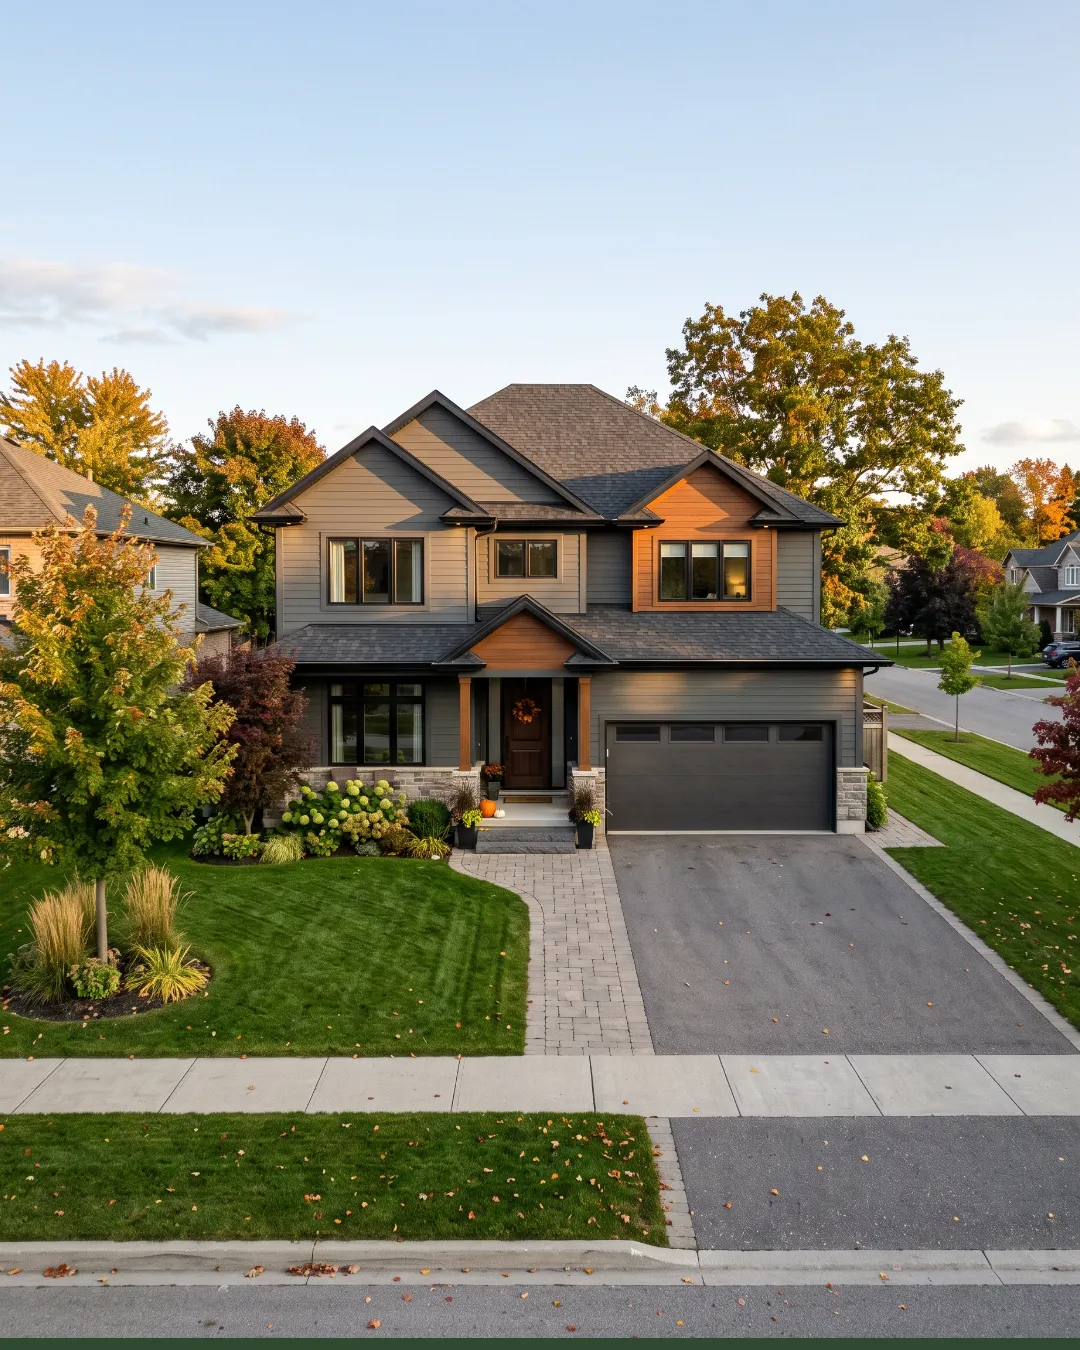
High-value home programs typically apply to properties with a replacement cost of $1 million or more. With average home prices in Oshawa, Whitby, and Ajax now well above $800,000, and custom builds and waterfront properties in Clarington and Scugog regularly exceeding $1.5–2 million, this is no longer a niche category.
But it's not just about the building. High-value home insurance also addresses households with:
- Fine art, antiques, or collectibles
- High-end jewellery or watches
- Extensive wine or spirits collections
- High-end electronics, audio/visual equipment
- Custom cabinetry, flooring, or finishes that standard policies may not fully replace
The trigger isn't just property value — it's the gap between what your current policy would pay and what it would actually cost to make you whole.
How Standard Policies Fall Short
Standard home insurance policies are designed for the median home. The coverage structure, sub-limits, and claims processes reflect that. When your home or its contents fall outside that profile, several problems emerge:
- Replacement cost limitations — standard policies use generic cost estimates to determine the insured replacement value. For a custom home with premium finishes, these estimates may be significantly below actual rebuild costs. If your policy limit is $900,000 but the true replacement cost is $1.4 million, you're carrying $500,000 in uninsured exposure.
- Contents sub-limits — standard home policies contain sub-limits for specific categories like jewellery ($5,000 is common), fine art, and electronics. If your watch collection alone is worth $30,000, the standard policy covers a fraction of it. Scheduled personal articles coverage is needed to close this gap.
- Claims handling — high-value home programs often include concierge-level claims service, dedicated adjusters familiar with custom construction, and access to approved contractors who understand high-end materials. Standard policies route you through a general claims process designed for volume, not complexity.
What High-Value Home Programs Offer
Specialty high-value programs from carriers like Chubb, Intact Prestige, and others are specifically engineered for this segment. Key features typically include:
- Guaranteed replacement cost — the insurer agrees to rebuild the home to its original standard regardless of the cost, even if it exceeds the policy limit. This eliminates the risk of being underinsured due to construction cost inflation.
- Agreed value on fine art and jewellery — instead of market-value settlement arguments, agreed value policies establish what an item is worth at the time of underwriting, payable without dispute at claim time.
- Higher liability limits — high-value households typically carry more liability exposure (household staff, frequent entertaining, high-profile properties). Umbrella liability coverage and higher base limits are common in premium packages.
- Risk management services — some carriers provide pre-loss services including property valuations, fire prevention assessments, and security consultations.
Flood and Water Damage: A Growing Ontario Concern
Properties in flood-risk areas — including parts of Durham Region near Lake Ontario and flood-prone watercourses — need specific water damage endorsements. Standard policies have tightened sewer backup and overland water limits significantly in recent years. High-value programs often offer more comprehensive water coverage with higher limits, which matters enormously when a finished basement with premium materials floods.
Getting the Right Coverage
The first step is understanding your actual replacement cost — not your market value, but what it would cost to rebuild your home to its current standard tomorrow. For custom homes, this requires a proper replacement cost appraisal, not a generic calculator estimate. A McCAM advisor can help arrange this and match you with the right high-value program based on your specific property and contents profile.
Is your home covered to its actual value?
McCAM's home insurance specialists help Durham Region and Barrie homeowners close the gap between their standard policy and what they actually need.